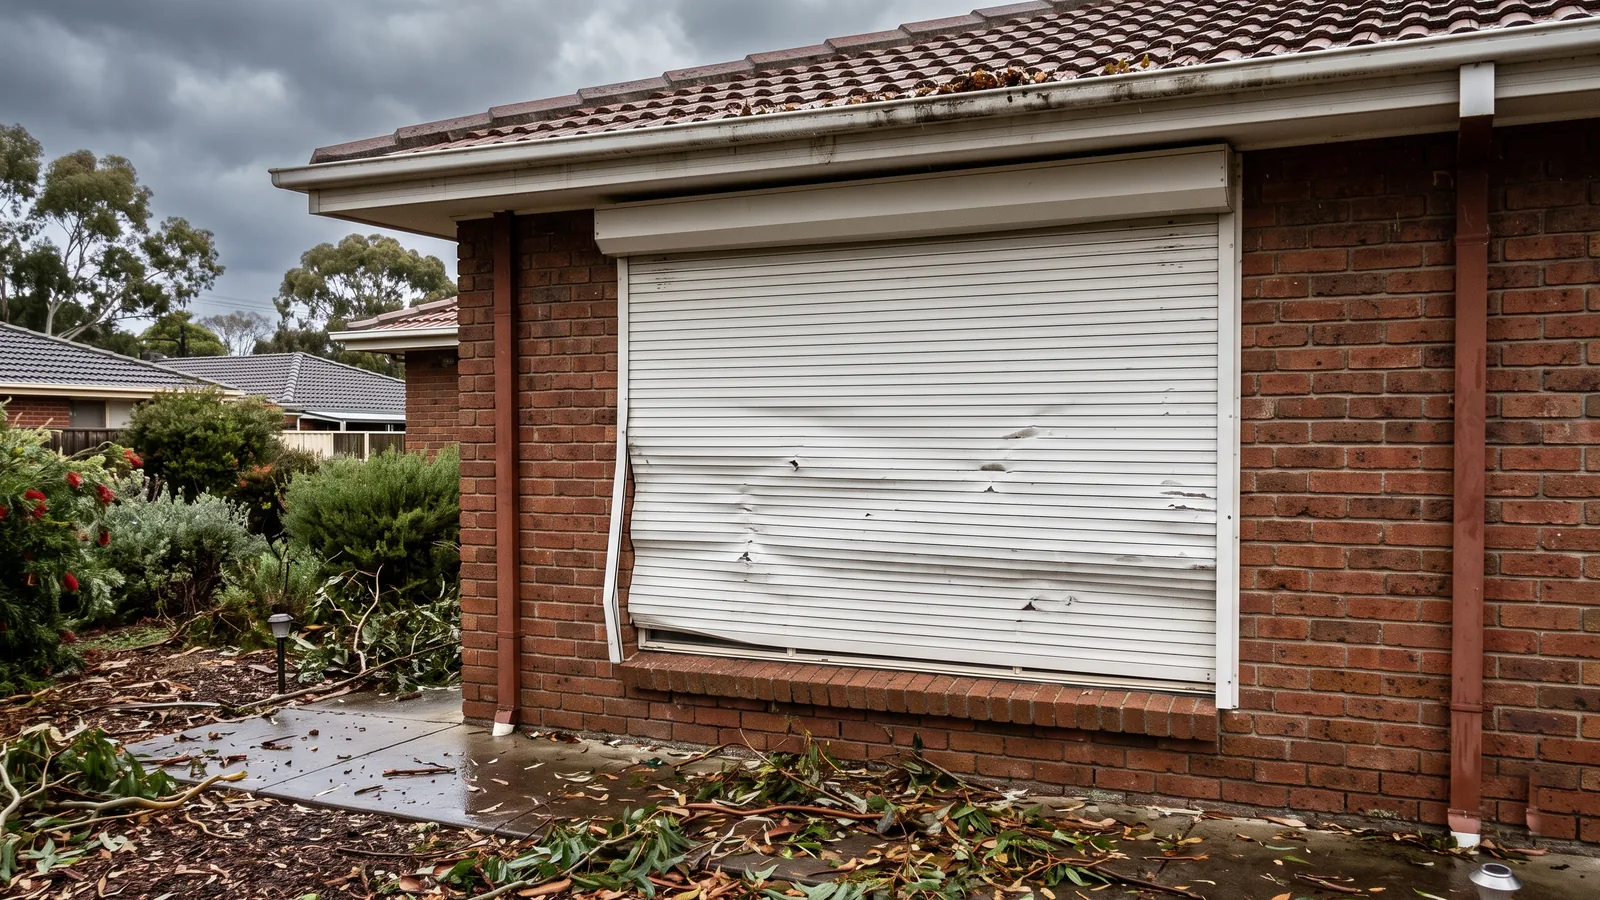
If a storm has ripped through your roller shutters or someone tried to force them open during a break-in, your first thought is probably whether insurance will cover a roller shutter insurance claim.
The short answer is yes, most home and contents policies do cover roller shutter damage. But the type of damage, how you document it, and when you lodge the claim all affect whether the insurer pays out or pushes back. Sydney cops its fair share of hailstorms, east coast lows, and break-ins, so this is a question Fix My Shutters fields regularly from homeowners across the city.
This guide walks through what gets covered, what gets knocked back, and how to give yourself the best chance of a smooth payout.
Home insurance covers roller shutter damage caused by sudden, unexpected events. The key word is "sudden." Gradual wear and tear is never covered.
Fixture vs fitting matters. Permanently installed roller shutters are covered under the "building" section of your policy. Removable shutters fall under "contents." The excess and coverage limits differ.
Claim denials are more common than most people expect. Knowing the reasons upfront gives you a chance to avoid the obvious pitfalls.
The Australian Financial Complaints Authority (AFCA) handles disputes when a claim is denied unfairly. It is a free service worth knowing about.
The process is straightforward if you stay organised. Rushing through it or skipping documentation is where most people come unstuck.
Have your claim reference number ready when you call for a quote. We deal with insurance jobs regularly and format quotes the way insurers expect, which avoids back-and-forth delays.
Even when your claim is approved, you will pay something out of pocket.
| Cost | Typical Range |
|---|---|
| Policy excess | $500 to $1,000 for residential |
| Slat replacement (repair) | $200 to $600 |
| Full shutter replacement | $900 to $2,500 per shutter |
| Motor replacement | $350 to $750 |
| Betterment (age-based depreciation) | Varies by insurer and shutter age |
If the repair cost is close to your excess, it may not be worth claiming and risking a premium increase at renewal. An experienced roller shutter repair specialist can give you an honest assessment of the numbers before you decide whether to claim or pay out of pocket.
Your insurer is obligated to put you back in the same position you were in before the damage. That means like-for-like, not an upgrade.
If you want to upgrade from manual to motorised during the replacement, the insurer covers the like-for-like cost only. The upgrade cost is yours. That said, it can be worth doing while the shutter is already being worked on, because the labour is already factored in.
Sydney sits in one of Australia's most active hail corridors. The Insurance Council of Australia (ICA) regularly declares catastrophe events for Sydney storms, which triggers faster claims processing.
After a declared catastrophe event, insurers are required to fast-track claims. Fix My Shutters has over 15 years of experience handling insurance repair jobs across Sydney and turns around quotes within 24 to 48 hours during storm season.
Yes, if the damage was caused by a sudden event like a storm, break-in, vandalism, or accidental impact. Wear and tear and lack of maintenance are not covered.
Date-stamped photos of the damage, a written quote from a licensed repairer, and the date the damage occurred. For break-ins, you also need a police report number.
Common reasons include wear and tear, pre-existing damage, late notification, and insufficient documentation. If a denial seems unfair, escalate to AFCA for free dispute resolution.
You can, but you pay the difference. Insurance covers like-for-like only. Switching from manual to motorised or upgrading the slat material costs extra.
Residential claims typically take 3 to 10 business days for approval. After a declared catastrophe event, processing can be faster.
Some insurers offer a 5 to 10 percent discount for homes with security roller shutters, particularly if they meet Australian Standard AS5039. Ask your insurer whether your shutters qualify.
If the shutter is part of the building exterior and classified as common property, the body corporate's building insurance covers it. If you installed it yourself within your lot, your own contents insurance applies. Check the strata by-laws to confirm.
For investment properties, the excess you pay on an insurance claim is generally tax-deductible. Talk to your accountant about claiming it in your next return.
A damaged roller shutter leaves your home exposed. Whether it is storm damage, a break-in, or accidental impact, the first step is a proper assessment and a detailed quote your insurer can work with.
Fix My Shutters has over 15 years of experience with roller shutter repairs across Sydney, including insurance work. We provide itemised quotes formatted for insurers and are happy to liaise with your insurance company directly. Contact us with your claim reference number and we will get it sorted.
